There was a lot to digest from Wednesday’s earnings reports from Microsoft and Google, long the No. 2 and 3 players in cloud computing, respectively. But let’s start with the most interesting takeaway: Google’s cloud unit revenues are now within spitting distance of Microsoft’s Azure cloud revenues, thanks in part to Google’s sales of its AI chips, known as tensor processing units. For those of us who remember the days not long ago when Google was an also-ran in cloud, that’s a pretty stunning development. But we’re getting ahead of ourselves. The stellar third-quarter growth in Google’s cloud computing business was overshadowed by other financial results that disappointed Wall Street analysts, particularly weak growth in Google’s search advertising revenues. Google’s stock dropped nearly 10% in after-hours trading. Microsoft’s growth, meanwhile, played better with investors, sending its stock up about 3% in after-hours trading (Microsoft shares are up 12% for the year, compared to 2% for Google). First, let’s look at Google’s numbers. Alphabet, the search giant’s parent company, reported a 25% jump in revenue to $127.58 billion, which fell slightly short of Wall Street forecasts. Due to its enormous spending on AI, the company showed negative free cash flow of over $9 billion compared to positive free cash flow of over $24 billion in the same period a year ago.
Thanks for reading The Briefing, our nightly column where we break down the day’s news. If you like what you see, I encourage you to subscribe to our reporting here.
Greetings!
There was a lot to digest from Wednesday’s earnings reports from Microsoft and Google, long the No. 2 and 3 players in cloud computing, respectively. But let’s start with the most interesting takeaway: Google’s cloud unit revenues are now within spitting distance of Microsoft’s Azure cloud revenues, thanks in part to Google’s sales of its AI chips, known as tensor processing units. For those of us who remember the days not long ago when Google was an also-ran in cloud, that’s a pretty stunning development.
But we’re getting ahead of ourselves. The stellar third-quarter growth in Google’s cloud computing business was overshadowed by other financial results that disappointed Wall Street analysts, particularly weak growth in Google’s search advertising revenues. Google’s stock dropped nearly 10% in after-hours trading. Microsoft’s growth, meanwhile, played better with investors, sending its stock up about 3% in after-hours trading (Microsoft shares are up 12% for the year, compared to 2% for Google).
First, let’s look at Google’s numbers. Alphabet, the search giant’s parent company, reported a 25% jump in revenue to $127.58 billion, which fell slightly short of Wall Street forecasts. Due to its enormous spending on AI, the company showed negative free cash flow of over $9 billion compared to positive free cash flow of over $24 billion in the same period a year ago.
The figures that seemed to alarm some investors the most were Google’s search revenues, which grew 12% to $63.35 billion—the softest growth in the business since the second quarter of 2025. Those results seemed discordant with the fact that people are using Google search more than ever. Alphabet CEO Sundar Pichai said Google’s year-over-year search query growth rate is the highest it has been in five years, which he attributed to the company’s AI investments.
But for the moment, Google isn’t showing as many ads in AI Mode, its AI-powered search results, as it typically does. “It’s worth noting the strong growth in AI Mode queries had an impact because of the lower monetization we were seeing in AI Mode,” Google Chief Business Officer Philipp Schindler said on a call with analysts, in explaining the disconnect.
Still, there were those Google Cloud results to admire. Revenue from that business more than doubled in the quarter to over $30 billion, while the unit’s operating income tripled to $11.12 billion. That revenue figure was just shy of Microsoft’s $33 billion in Azure revenues for the period, which grew 48%. If Google Cloud keeps up its superior growth rate, it won’t be long before the business is bigger than Azure.
Of course, the comparison isn’t totally apples-to-apples. Google Cloud revenues include a burgeoning server hardware business, through which the unit sells TPU systems to customers that put the chips in their own data centers. Google didn’t disclose exactly what its TPU sales were in the quarter, though it did say they were a “meaningful contributor to revenue growth.” Google executives primed analysts to expect TPU sales to have an even bigger impact on Google Cloud next year.
“We’re seeing extraordinary demand,” Thomas Kurian, Google Cloud’s CEO, told them.
Less is More at Microsoft
Last month, when Microsoft announced it was overhauling how it reports its business segments’ quarterly results, CEO Satya Nadella promised “increased transparency.” Today though, one figure they had disclosed in the prior quarters—the number of paying users of its flagship Copilot AI software—was conspicuously absent.
Previously, the company had said it had 30 million paying users of Copilot as of the end of June, up from 15 million at the end of 2025. Those customers each pay a $30 per month fee to use Copilot in its Office and Teams software, on top of fees they pay separately for those applications.
That solid growth planted Microsoft’s flag as the second-biggest seller of AI software after OpenAI, and helped assuage some investors’ concerns about whether Microsoft’s core enterprise software business was getting returns from its ballooning AI spending. The company’s decision to stop disclosing the figure raises the question of whether Copilot subscriptions are growing as robustly as they had in the past.
The good news for Microsoft is that its AI-infused software business still seems to be strong. Revenue in its 365 Commercial Cloud unit—which includes Copilot as well as sales of its broader suite of Office software—rose 17% to $27.7 billion, a slight acceleration from the June quarter. Overall revenue rose 19% to $92.3 billion in the September quarter, 1 percentage point faster than the growth it reported in the prior quarter.
There are other reasons Microsoft might want to get investors to pay less attention to the growth of per-seat subscriptions of Copilot. The company overhauled its Copilot software late last month to combine various features under one application; part of the reason for the change was to steer Copilot users towards newer features like agents that compete with Meta’s Muse and vibe-coding tools, which are billed on a pay-as-you-go basis. In other words, Microsoft is now trying to get more Copilot revenue growth to come from people using the software more, rather than just from selling additional seats.
Nadella hammered this point during Wednesday’s call with analysts, stating that the number of customers paying for usage-based features in Copilot grew 75% in the September quarter, and CFO Amy Hood said average revenue per user grew thanks to increased use of the pay-as-you-go AI tools.
Whether Microsoft can keep its AI software revenue growth going will be more telling, especially as it starts to offer steeper per-seat discounts on the software in a broader pricing war with the likes of OpenAI and Anthropic.—Aaron Holmes
In Other News
Apple launched its first touchscreen computer, the MacBook Pro with PROLED XDR Display, which will start at $2,899. That’s a steep premium to its latest MacBook Pro without a touchscreen, which starts at $1,999.
Oracle provided a roadmap for when its capital expenditures will begin to slow, describing fiscal 2028 and 2029 as a “period of peak capex.” The company’s free cash flow will turn positive in fiscal 2028 and exceed $30 billion in fiscal 2029, it said. Oracle’s shares rose 10%.
Google launched Gemini 4 Carbon, the company’s second major model release in a month.
Marvell is in advanced talks to buy data center optics maker Lumentum.
Today on The Information’s TITV
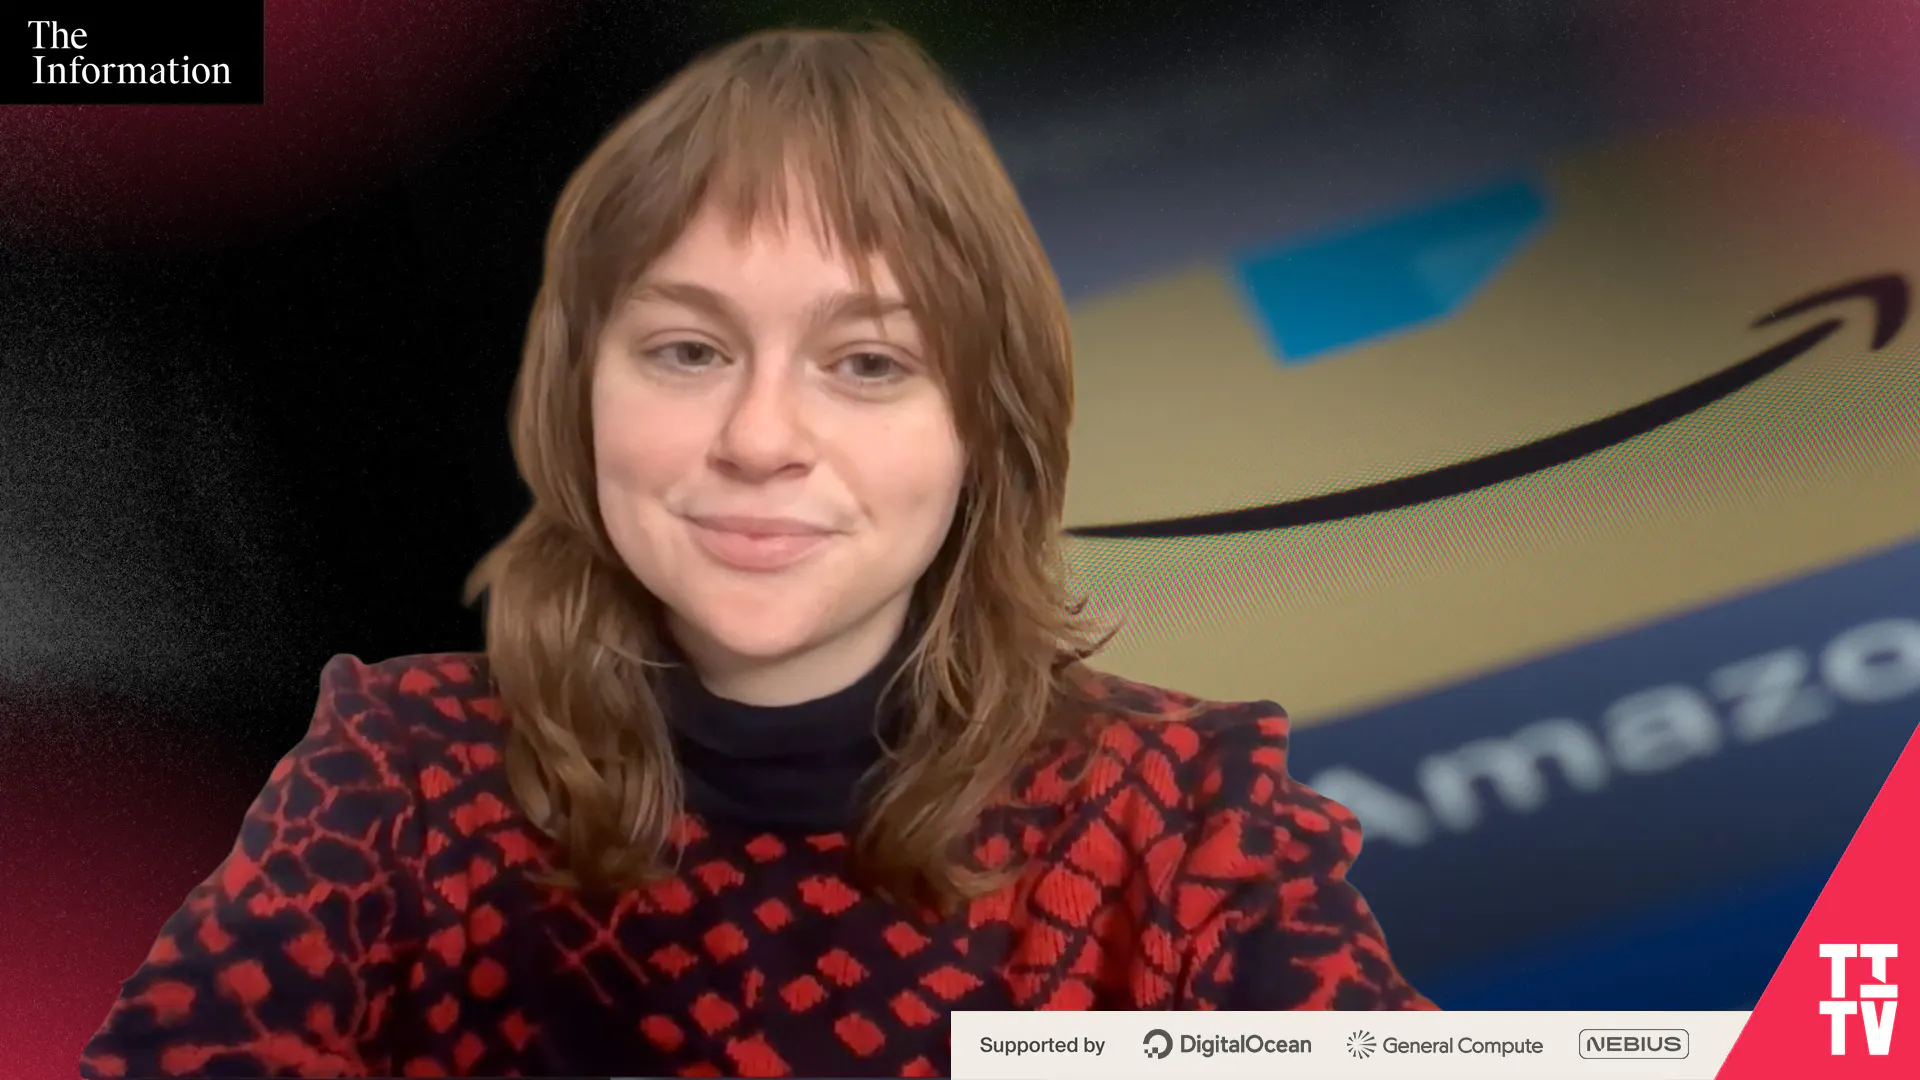
Check out today's episode of TITV in which Akash Pasricha speaks with Catherine Perloff about her reporting on Amazon's defense against agent-induced disintermediation.
Recommended Newsletter
Start your day with Applied AI, the newsletter from The Information that uncovers how leading businesses are leveraging AI to automate tasks across the board. Subscribe now for free to get it delivered straight to your inbox twice a week.
Trust is quickly becoming the defining question of the AI era. Over dinner, Jessica Lessin, Founder & Editor-in-Chief of The Information, and Whitt Butler, EY Americas Vice Chair – Consulting, will talk candidly about how leaders can build that trust and keep it. Request an invite.
Join The Information and NYSE for a cocktail reception and conversation on what it really takes to go public, hosted by The Information’s Dakin Campbell. The panel will explore the trust, relationships and preparation companies need to build with advisers, investors and exchange executives, along with the many complexities founders and executives must navigate along the way. Sponsored by NYSE. Apply to attend.



 Gift Subscription
