 | ||||||
 | ||||||
We had a fully written special issue ready to drop in your inbox this week—but then, in case you hadn’t noticed, some market stuff happened. Democrats took control of both the House and Senate in Tuesday’s midterm elections, which sent stocks up on Wednesday … only for the market to log its worst day since “Liberation Day” on Thursday. So we put this issue together instead. Below…
| ||||||
 | ||||||
| Illustration by Allie Sullberg/Wealthfront | ||||||
 | ||||||
| One number that explains the economic moment | ||||||
| ||||||
 | ||||||
 | ||||||
| Did the blue wave knock over AI’s sand castle? | ||||||
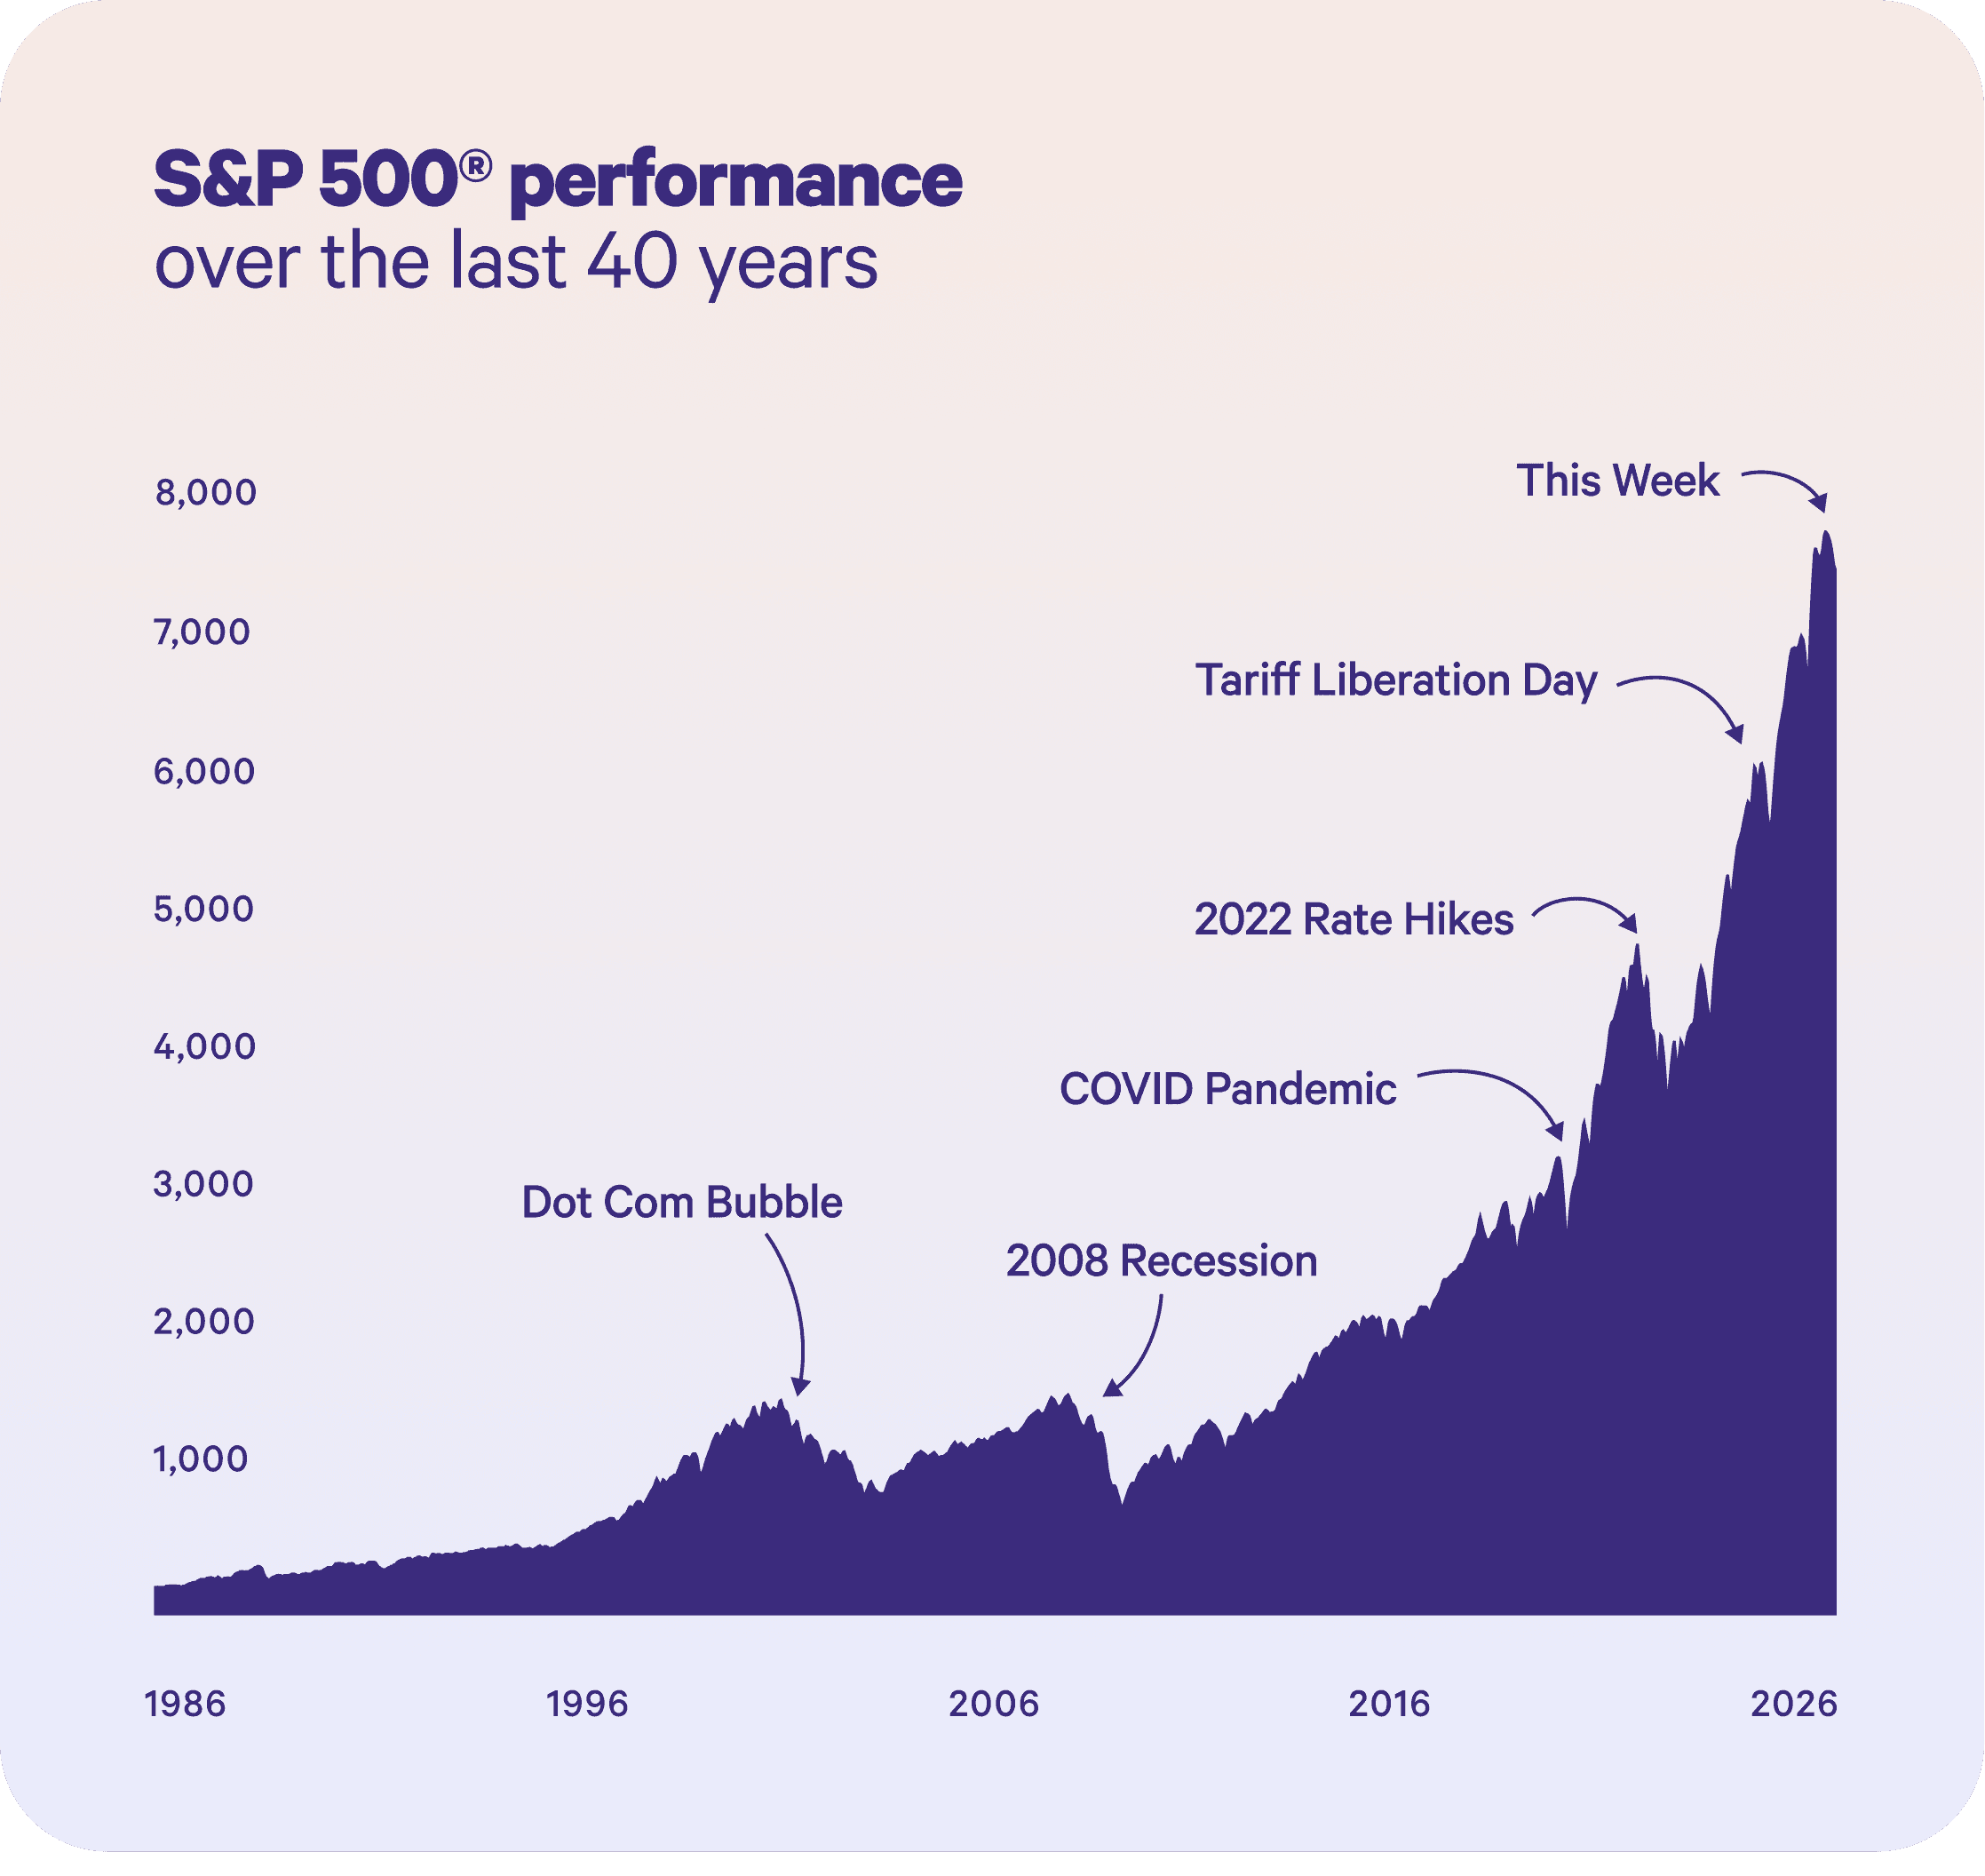 | ||||||
Source: Yahoo Finance. Image by Wealthfront. A blue wave on Tuesday ushered in a red wave on Thursday, as investors “retreated from the AI trade”—which is to say that they sold basically every stock with an AI connection en masse, pushing prices down. The Mag 7 shed about $1 trillion in market cap and the tech-heavy Nasdaq-100® closed down more than 6%—a drop of almost 15% from October’s peak, which puts it into “correction” territory. (Information in this newsletter is accurate as of market close the day before publication, but is subject to change.) The S&P 500 posted its worst day since April 2025, the 500 individuals on Bloomberg’s Billionaires Index collectively lost $185 billion, 13 of Goldman Sachs’ AI-related portfolios had their worst day since ChatGPT launched, and retail traders sold the most stocks in one day since March 2020. Oh, and oil prices went up. Why did it happen and what does it mean? Let’s get into it. LLM: Large Language Mandate As mentioned earlier, AI was very much on the ballot on Tuesday, and voters in key capacity-buildout states like Texas, Georgia, and Ohio—where, together, 40% of US data center builds are planned—elected a lot of overtly AI-skeptical officials. Democratic Texas governor-elect Gina Hinojosa has vowed to halt approvals of new facilities until a “legislative session that puts Texans first,” while Ohio senator-elect Sherrod Brown ran a campaign in which he referred to his opponent as the “face of data centers.” Why? The simplest explanation is that the data center boom has helped raise the average American’s monthly electric bill by 10% since 2024 in a period when inflation was already a top concern. Gas prices are up 33% since last year amid the war in Iran, and consumer sentiment is hovering around all-time lows. Data centers’ environmental impact has also become a bipartisan issue, while 71% of respondents to a recent Pew survey said they believe that AI will reduce the number of jobs available (to humans). Why that matters to the money people The election results have seemingly rattled the market’s faith in the data center buildout timelines promised by the world’s biggest tech companies, which in turn raises questions about if those companies can hit their targets for developing and profiting from AI. Since much of the AI infrastructure buildout is being funded with debt, slowdowns can create a sizable risk. Some hyperscalers, like Meta, are reportedly considering alternatives like building data centers outside of the US or expanding existing projects. In a post on X, Elon Musk re-floated the idea that an easier path might be putting them in space. In a case of awkward timing, Alphabet announced a $17 billion plan to build its first data center in Wyoming on Thursday—but in a nod to the times, pledged to “pay for 100% of the power” it uses. Midterms are usually market-friendly Despite the Thursday of it all, midterms have historically ushered in market gains. Per Goldman Sachs, the S&P 500 has risen 15.5%, on average, in the 12 month period after midterms, dating back to 1954. According to CNBC, the S&P 500 rose an average of 11% in the year following a midterm election in which Democrats took or retained control of the House and Senate while a Republican held the White House (1986, 1990, and 2006). The hypothesis there is that divided governments tend not to spend irresponsibly because they can’t agree on what to spend on, which might have been one reason why stocks actually went up on Wednesday morning as vote tallies rolled in. Of course (tapping the sign), past performance is not indicative of future results, and things like Federal Reserve policy, earnings reports, and energy prices tend to have a bigger impact on markets than elections. The takeaway Thursday’s events are an echo of 2025’s Liberation Day crash, when the S&P 500 posted its worst week since Covid in response to the administration’s announcement of its intentions to impose heavy tariffs on imports. When China’s decision to apply reciprocal tariffs was announced, all but 14 of the index’s 500 constituents found themselves in the red. A year later, though, the index was up 16%. That’s not a guarantee that the same thing will happen in the coming 12 months, but it’s a good reminder that what’s happening in the market is the result of many, many actors speculating at once in real time about what a variety of events might mean, and then responding to each others’ responses, and on and on. (The oil market, it’s said, is “mulling over” Iran possibilities, and on Thursday it felt differently than it did Wednesday. Let us know when you decide, guys!) For the individual investor, the good news is that not trying to play this game—simply leaving one’s money invested without accruing the transaction costs or potential losses associated with speculating on the future—has been a good way to win in the long run for a long time. Share this story | ||||||
| ||||||
 |

The Standard & Poor’s 500 Index is a capitalization weighted index of 500 stocks designed to measure performance of the broad domestic economy through changes in the aggregate market value of 500 stocks representing all major industries. The Nasdaq-100 Index® is a modified market-capitalization-weighted index composed of 100 of the largest non-financial companies listed on the Nasdaq Stock Market. Indices are not available for direct investment; therefore, their performance does not reflect the expenses associated with the management of an actual portfolio. Passive investing may help minimize certain risks, it does not eliminate market risk or guarantee higher returns. Unlike retirement accounts (such as 401(k)s and IRAs), taxable investment accounts may be subject to capital gains taxes on withdrawals, and short-term market fluctuations could impact returns. Personal circumstances, goals, and time horizons can affect investment outcomes. Please consult with a professional tax adviser to discuss your specific situation. Diversification and automated investing do not guarantee profit or ensure against loss. Investor experiences can vary widely based on strategies and time horizons. Index funds and ETFs generally offer broad diversification, but may still expose investors to specific market, sector, or asset class risks. Wealthfront provides investment management services but may not achieve returns comparable to those of the general market or specific benchmarks. The information contained in this communication is provided for general informational purposes only, and should not be construed as investment or tax advice. Nothing in this communication should be construed as a solicitation, offer, or recommendation, to buy or sell any security. Any links provided to other server sites are offered as a matter of convenience and are not intended to imply that Wealthfront Advisers or its affiliates endorses, sponsors, promotes and/or is affiliated with the owners of or participants in those sites, or endorses any information contained on those sites, unless expressly stated otherwise. All investing involves risk, including the possible loss of money you invest, and past performance does not guarantee future performance. Please see our Full Disclosure for important details. Investment management and advisory services are provided by Wealthfront Advisers LLC (“Wealthfront Advisers”), an SEC-registered investment adviser, and brokerage related products are provided by Wealthfront Brokerage LLC ("Wealthfront Brokerage"), a Member of FINRA/SIPC. Wealthfront Advisers and Wealthfront Brokerage are wholly-owned subsidiaries of Wealthfront Corporation.
|